H2: Four government-backed routes to compare
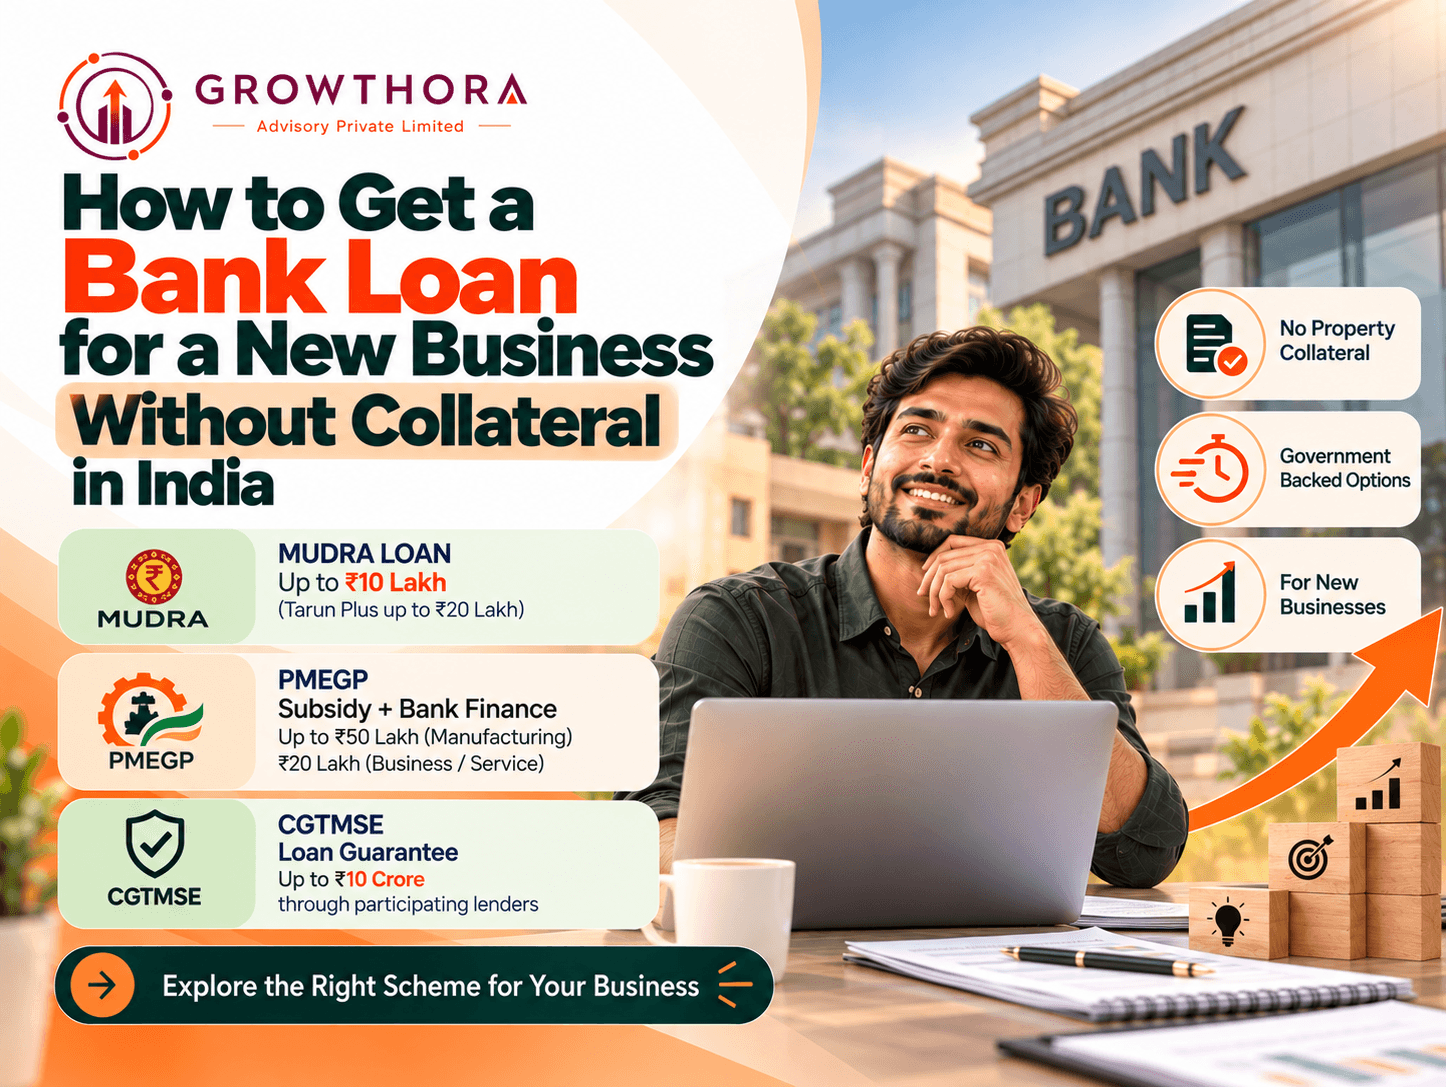
There is no single best scheme for every business. Compare the purpose, project size, eligibility and whether the support is a direct loan, a subsidy linked to a bank loan or a credit guarantee.
| Route | What it does | Best fit | Key caution |
|---|---|---|---|
| PMEGP | Bank finance with eligible margin-money subsidy for qualifying new units | Eligible new manufacturing and business/service projects that meet PMEGP rules | Subsidy is not paid as unrestricted cash to the applicant; project, contribution, training and lock-in conditions apply |
| CGTMSE | Credit guarantee to a participating lender for eligible MSE credit | Eligible micro and small enterprises needing term loan and/or working capital, including larger cases | CGTMSE does not lend directly. The lender decides whether to sanction and seek guarantee cover |
| MUDRA / PMMY | Collateral-free institutional credit for eligible income-generating micro businesses | Small traders, service providers, manufacturers and eligible allied-agriculture activities | Tarun Plus up to ₹20 lakh is for eligible borrowers who successfully repaid a prior Tarun loan |
| Stand-Up India | Original scheme offered ₹10 lakh to ₹1 crore composite loans for eligible greenfield enterprises owned by women or SC/ST entrepreneurs | Potentially relevant only after current availability is verified | Original scheme period ended 31 March 2025. Do not assume fresh applications are currently open under the original scheme |
H2: 1. PMEGP: Consider it if you are setting up an eligible new unit
The Prime Minister's Employment Generation Programme (PMEGP) combines bank finance with a government margin-money subsidy for eligible new micro-enterprises. It is not simply an unsecured loan product. The application is assessed under PMEGP rules and the bank separately evaluates whether the project can repay the loan.
PMEGP project limits and subsidy rates
| Item | Manufacturing | Business / service |
|---|---|---|
| Maximum project cost eligible for margin-money subsidy | ₹50 lakh | ₹20 lakh |
| General category subsidy | 15% urban; 25% rural | 15% urban; 25% rural |
| Special category subsidy | 25% urban; 35% rural | 25% urban; 35% rural |
| Own contribution | Generally 10% for general category; 5% for special category | Generally 10% for general category; 5% for special category |
| Category | Loan amount |
|---|---|
| Shishu | Up to ₹50,000 |
| Kishore | Above ₹50,000 and up to ₹5 lakh |
| Tarun | Above ₹5 lakh and up to ₹10 lakh |
| Tarun Plus | Above ₹10 lakh and up to ₹20 lakh, for eligible entrepreneurs who have successfully repaid a previous Tarun-category loan |
These rates describe the standard PMEGP framework and are subject to the current guidelines, beneficiary category, location classification and project eligibility. The subsidy is margin-money assistance routed through the scheme and bank process, not a cash discount handed to the applicant at the start. The bank finances the balance according to the approved structure.
Who should consider PMEGP?
An individual aged 18 or above who is planning an eligible new micro-enterprise.
An applicant with a realistic project report, quotations and a clear explanation of how the business will earn.
A project that fits the permitted activities and the current PMEGP guidelines.
Someone who can arrange the required own contribution and complete any applicable entrepreneurship development training.
Before applying, verify whether your activity is permitted, whether the project cost is within the relevant limit and whether you meet the education or other conditions applicable to the project size. Existing units and projects that do not qualify as new units may be treated differently.
H2: 2. CGTMSE: Ask the bank whether your MSE loan can be covered
The Credit Guarantee Fund Trust for Micro and Small Enterprises (CGTMSE) is often misunderstood. It does not give the entrepreneur a loan directly. It provides a credit guarantee to eligible member lending institutions for qualifying credit facilities extended to eligible micro and small enterprises. That guarantee can help a lender consider a loan without collateral security or a third-party guarantee, subject to the scheme and lender's credit policy.
How much finance can be covered?
CGTMSE's current published scheme information allows eligible credit facilities up to ₹10 crore per eligible borrower for specified participating lenders, subject to the scheme rules. Different lender categories can have different limits. The ₹10 crore figure is a ceiling for eligible facilities, not an entitlement to receive that amount and not a promise that every loan will be fully guaranteed.
How to raise CGTMSE with your bank
Prepare a project report showing the product or service, target customers, expected sales, costs, working-capital cycle and repayment plan.
Apply to a bank or other lender that is a CGTMSE member lending institution.
Ask the credit officer whether your proposed term loan or working-capital facility can be considered under CGTMSE, and whether the activity and borrower meet the scheme rules.
Ask the lender to explain any primary security, promoter contribution, guarantee fee or other charges that apply.
Keep in mind that the lender assesses the proposal first. The guarantee reduces eligible lender risk; it does not remove the borrower's repayment obligation.
If the bank asks for property collateral, do not assume the conversation is over. Ask whether the proposal can be assessed under the applicable credit guarantee route, including CGTMSE if your enterprise and facility qualify. The bank may still decline the proposal if the business cash flow, credit history or documentation is weak.
H2: 3. MUDRA: A practical route for smaller micro-business requirements
Pradhan Mantri Mudra Yojana (PMMY) supports eligible income-generating micro-enterprises through participating banks, regional rural banks, small finance banks, NBFCs and microfinance institutions. It can suit a small shop, repair service, food business, local manufacturer or another eligible micro-enterprise that needs a modest amount of finance
H2: What banks check when you do not pledge property
When a lender cannot rely on a house or plot as collateral, it still needs a credible reason to believe the business will repay. There is no single CIBIL score or promoter-contribution percentage that guarantees approval across every bank and scheme. The points below are common areas of assessment, not universal eligibility rules.
1. Credit history and repayment behaviour
A clean credit history helps. A score around 700 or higher can be a useful personal benchmark, but it is not a universal approval cutoff. Banks may use their own scorecards and review existing loans, repayment delays, overdue accounts, credit utilisation and the applicant's overall financial behaviour. Check your credit report before applying and correct genuine errors.
2. Project viability and cash flow
Your report should show how the business will generate enough cash to pay operating expenses, taxes, household or promoter withdrawals where relevant, and loan instalments. Avoid sales forecasts that jump sharply without evidence. Use supplier quotations, customer enquiries, local demand, realistic margins and a month-by-month cash-flow estimate.
3. Own contribution and working capital
The amount you must bring yourself depends on the scheme, bank, project and borrower category. PMEGP has specified beneficiary-contribution rules. Other products may have lender-specific margin requirements. Do not assume that every collateral-free loan requires exactly 10%, 20% or 25% promoter contribution.
4. Business experience and operational readiness
Relevant work experience, a qualified team, identified premises, licences where required and a practical launch plan can make the proposal easier to assess. A new entrepreneur can still apply, but should be ready to explain how the business will operate from day one.
5. Documents and consistency
Make sure your application, project report, quotations, bank statements, identity details, address details and registrations agree with one another. Inconsistent project costs or unexplained deposits can slow down appraisal.
H2: Documents to prepare before approaching a bank
- PAN, identity proof, address proof and photographs, as requested by the lender.
- Business constitution documents, such as proprietorship details, partnership deed or company documents, as applicable.
- Udyam Registration where applicable, plus GST registration or other licences if required for the activity.
- A bankable Detailed Project Report (DPR) with project cost, means of finance, sales assumptions, operating costs and repayment estimates.
- Quotations for machinery, equipment, inventory or other proposed purchases.
- Bank statements and income or tax documents available for the applicant and business.
- Proof of own contribution and source of funds, where required.
- Premises details, lease or ownership documents, and sector-specific approvals where applicable.
- For an existing business, available financial statements, GST returns, sales records, existing loan details and receivables/payables information.
The exact checklist differs by lender, scheme, project size and business activity. Ask the bank for its current checklist before submitting originals or paying for third-party services.
H2: How to improve your chances of approval
- Choose the scheme after defining the business, not the other way around. Write down the project cost, funding gap and intended use of every rupee.
- Build a realistic DPR. Include a market overview, customer profile, competitor context, equipment quotations, staffing, operating expenses and a repayment plan.
- Keep the requested loan proportionate to the business. A smaller, evidence-backed request can be easier to justify than an inflated project budget.
- Prepare a monthly cash-flow forecast and stress-test it. Ask whether the business can still pay the instalment if sales are 15% to 20% below your base case.
- Check your credit report and resolve avoidable issues before applying.
- Ask the lender direct questions: Is this activity eligible? Is collateral-free assessment possible? Can the facility be considered under a relevant guarantee? What are the margin, fees, interest rate and repayment terms?
- Use official portals and lender branches. Be cautious of anyone promising guaranteed sanction, guaranteed subsidy or a government connection in exchange for an advance fee.
H2: Common mistakes that weaken a collateral-free loan application
- Treating a scheme ceiling as a guaranteed loan amount.
- Assuming CGTMSE is a direct lender or that it pays the entrepreneur.
- Calling every loan without property collateral completely unsecured. Banks may still take primary security over assets financed by the loan.
- Using inflated sales projections without customer, market or pricing evidence.
- Ignoring working capital, taxes, insurance, maintenance and the time it takes to build sales.
- Assuming a single CIBIL score or promoter-contribution percentage applies to all banks and schemes.
- Relying on old Stand-Up India scheme details without verifying current application status.
- Paying an agent who guarantees approval or claims to control the subsidy release.
H2: Frequently asked questions
Can I get a business loan without collateral for a new business in India?
It may be possible. Eligible applicants can explore MUDRA, PMEGP-linked bank finance and loans considered for CGTMSE guarantee cover. Approval depends on the scheme rules, lender appraisal, project viability, credit history and documents.
Which government scheme gives a collateral-free business loan?
There is no single scheme for every borrower. MUDRA supports eligible micro-enterprise loans, PMEGP links bank finance with margin-money subsidy for qualifying new units, and CGTMSE provides guarantee cover to participating lenders for eligible MSE credit.
Can I get ₹20 lakh under MUDRA as a first-time borrower?
Tarun Plus offers loans above ₹10 lakh and up to ₹20 lakh to eligible entrepreneurs who have successfully repaid a previous Tarun-category loan. A first-time borrower should not assume they qualify for Tarun Plus.
Does CGTMSE give loans directly to entrepreneurs?
No. CGTMSE provides a credit guarantee to eligible member lending institutions. The bank or other participating lender appraises the proposal, decides whether to sanction the loan and applies for guarantee coverage under the applicable rules.
Can CGTMSE cover a loan of ₹1 crore or ₹5 crore?
Eligible credit facilities up to ₹10 crore can be covered under the current scheme for specified participating lenders, subject to eligibility and scheme conditions. This is a ceiling, not a promise of sanction or full guarantee coverage.
Does collateral-free mean I do not need to provide any security?
Not necessarily. A lender may take primary security over assets purchased with the loan, and may require margin money or other conditions. Collateral-free generally refers to not requiring additional collateral security or a third-party guarantee under the relevant product or scheme.
Is a CIBIL score of 700 compulsory for a collateral-free business loan?
There is no universal 700 cutoff that applies to every scheme and lender. A stronger credit profile can help, but banks assess repayment history, existing liabilities, business cash flow, documents and their own credit criteria.
Is PMEGP subsidy available for every new business?
No. PMEGP applies only to eligible projects and beneficiaries under the current guidelines. Activity restrictions, project-cost limits, contribution requirements and other conditions apply. Confirm eligibility through the official PMEGP portal before planning around the subsidy.
Is Stand-Up India still accepting new applications in 2026?
The original Stand-Up India scheme period ended on 31 March 2025. A successor programme was announced in the 2025-26 Budget, but its current notification and application status should be verified through official government sources or a participating bank before relying on it.
Can a bank reject my application even if I meet a government scheme's basic eligibility?
Yes. Basic eligibility does not guarantee sanction. The lender still assesses project viability, repayment capacity, credit history, documentation and compliance with the scheme and its own lending policy.
H2: Let Growthora help you prepare a stronger application
The goal is not simply to find a scheme with a large headline limit. It is to identify a route that fits your business, prepare a credible project report and present the numbers in a way a lender can evaluate.
Let Growthora evaluate your profile and help you identify a suitable collateral-free funding route for your enterprise.
Before you proceed, have your project cost, location, business activity, own contribution, expected sales and required loan amount ready. Scheme eligibility and bank approval remain subject to the applicable official rules and the lender's decision.
Next step
Apply this to your business.
Confirm whether this applies to your legal structure, industry classification, and credit history - in under 30 minutes with an advisor.